08/10/2026
Global wheat prices are strengthening, but not because the world is running short of wheat, according to new research from agribusiness banking specialist Rabobank.
In its just-released report From Hormuz to El Niño: Global disruption, not wheat shortages, is driving Australian wheat prices, the bank’s RaboResearch division said current market strength is being driven by growing disruption to global grain trade, rising freight and insurance costs and broader geopolitical instability – all of which are reshaping both wheat prices and production costs for wheat growers, including in Australia.
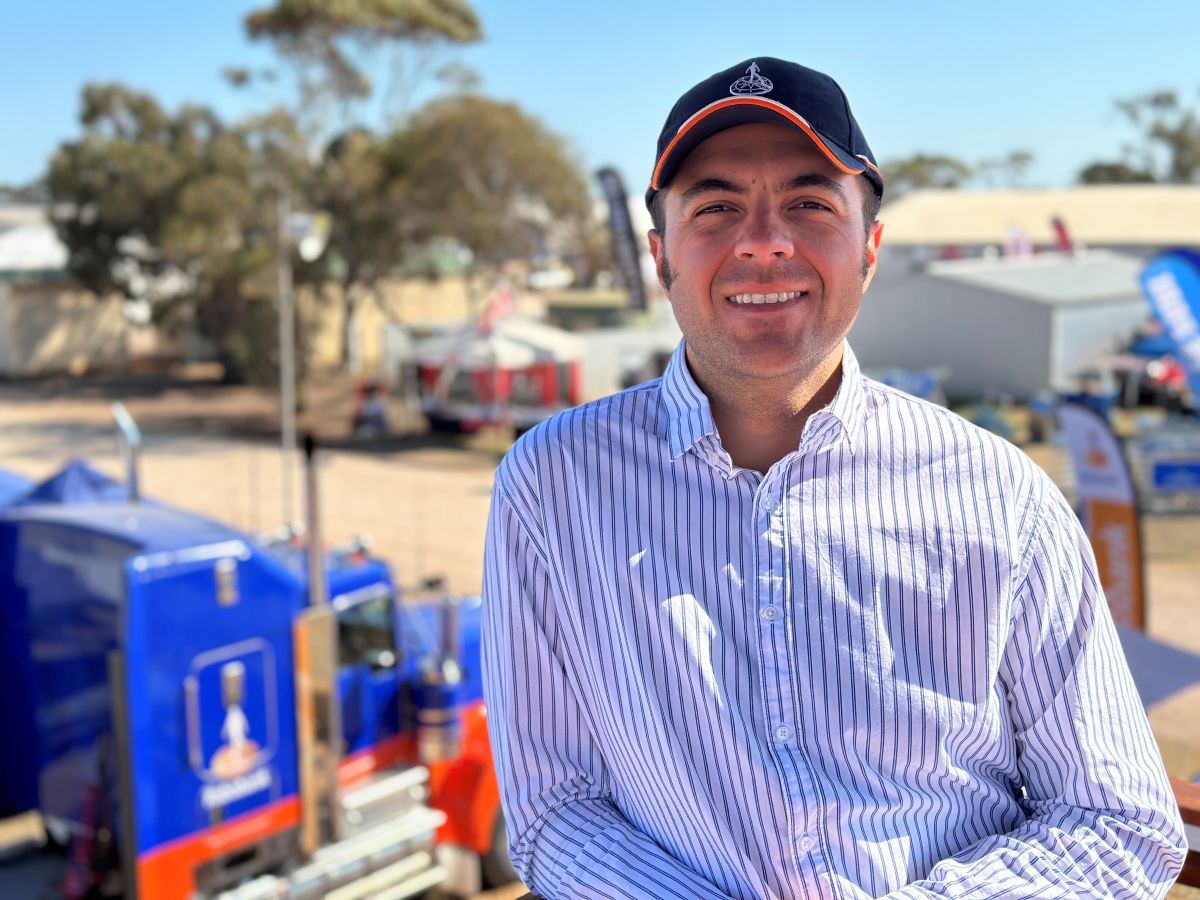
RaboResearch senior grains and oilseeds analyst Vitor Pistoia
Report author, RaboResearch senior grains and oilseeds analyst Vitor Pistoia said the market was “pricing” the reliability of grain flows rather than an outright shortage of wheat.
“The world is not short of wheat. The challenge is getting grain to buyers reliably and at an acceptable cost,” Mr Pistoia said.
“Current wheat prices reflect geopolitical risk and supply-chain disruption more than supply scarcity.”
And while global conflict is reshaping grain markets, the report says Australian growers are also beginning to focus on another potential market-moving factor, the prospect of El Niño conditions emerging in 2027.
Mr Pistoia said El Niño could lift eastern Australian wheat prices if it contributes to lower winter rainfall and reduced production as is typically associated with the event.
2027 prices
RaboResearch said wheat futures markets point to stronger prices into 2027. In early October, the 2026 CBOT wheat forward curve was largely pricing in a drop in Black Sea wheat exports, with prices into mid-2027 pointing toward the AUD 365 to AUD 370/tonne range, compared with AUD 325 to AUD 335/tonne three months earlier, Mr Pistoia said.
Australian port prices are expected to broadly track movements in international markets and could remain well supported while export disruption persists, he said. However, the report cautions that some of the current premium could disappear if geopolitical conditions improve.
“Markets remain highly sensitive to overseas military and diplomatic developments,” Mr Pistoia said.
“If we see a ceasefire, a new export agreement or a restoration of Black Sea export capacity, part of the current risk premium could unwind relatively quickly.”
Black Sea disruption
Russia and Ukraine had harvested strong wheat crops in 2026, the report said, with their combined production estimated at around three per cent above the five-year average and unchanged year on year. However, disruption to export infrastructure and shipping routes is expected to have reduced wheat exports from the region by approximately seven million tonnes between July and September compared with typical levels.
The expected reduction is nearly 50 per cent below normal export volumes for the period and equivalent to about four per cent of annual global wheat trade. While significant, it does not though constitute a global wheat shortage, the report said.
“What we are seeing in wheat prices is a risk premium rather than an outright wheat shortage,” Mr Pistoia said.
“Disruption to ports, vessels and shipping routes has reduced export reliability and increased freight and insurance costs. Grain is still being produced. The challenge is moving it.”
The report says Black Sea exporters are increasingly relying on alternative logistics pathways, including Danube barge routes through Romania, rail and road transport through neighbouring countries and alternative Russian export corridors via Baltic and Arctic ports.
These routes help maintain trade flows but are generally more expensive and less efficient than traditional export channels, it says.
Australia’s freight edge
For Australian growers, disruption to the Red Sea and other major shipping routes could improve the relative competitiveness of local grain exports, particularly into Asian markets, RaboResearch says.
“Australia is well positioned in key Asian export markets compared with northern hemisphere exporters facing longer and potentially more disrupted shipping routes,” Mr Pistoia said.
“Indicative sailing times to Indonesia are around eight days from Australia’s west coast and about 10 days from the east coast. Grain shipped from France or the Black Sea via the Cape of Good Hope can take around 40 days. That freight advantage becomes increasingly valuable when global shipping networks are under pressure.”
The report says this advantage could strengthen the basis for Australian grain into 2027, although the benefit to growers may be partly offset by rising input and freight costs.
Fertiliser concerns
While wheat prices have strengthened, the report warns production costs remain a major concern. Disruption affecting the Strait of Hormuz, the Red Sea and the broader Middle East is influencing energy markets, fuel costs, freight and fertiliser supply chains.
“For Australian growers, stronger grain prices are welcome, but higher input costs continue to erode margins,” Mr Pistoia said.
“Diesel, fertiliser and freight costs are being affected by many of the same geopolitical pressures supporting grain prices. In some cases, production costs have risen more sharply than wheat prices.”
The report notes diesel typically accounts for around four to six per cent of on-paddock operating costs, while continuity of supply can be more important operationally than its share of total costs. Fertiliser presents the larger planning and profitability risk because procurement decisions often need to be made months ahead and fertiliser is frequently the largest variable cost in wheat production.
“Typical diesel lead times are around 30 to 40 days, while fertiliser deliveries can take several months,” Mr Pistoia said.
“That means fertiliser presents a much larger planning and budget risk for growers.”
El Niño threat
The report also identifies weather as an increasingly important factor beyond the current season. While the impact of El Niño on the 2026/27 crop is expected to be limited, the larger risk is for eastern Australian grain production in 2027/28 if the event contributes to lower winter rainfall and reduced yields.
Reduced production in the eastern states could support national grain prices and shift a greater share of export activity towards Western Australia and South Australia, RaboResearch says.
Mr Pistoia said growers would be focussing on managing both grain-marketing opportunities and input-procurement risks in what is likely to remain a volatile global environment.
“Positive margins can still be achieved during periods of elevated costs, as we have seen previously,” he said.
“The challenge for growers is managing the timing, volatility and scale of both wheat-price and input-cost movements. The opportunities are there, but disciplined risk management will be critical.”
RaboResearch Disclaimer: Please refer to Australian RaboResearch disclaimer here
Rabobank Australia & New Zealand Group is a part of the international Rabobank Group, the world’s leading specialist in food and agribusiness banking. Rabobank has more than 125 years’ experience providing customised banking and finance solutions to businesses involved in all aspects of food and agribusiness. Rabobank is structured as a cooperative and operates in 35 countries, servicing the needs of more than nine million clients worldwide through a network of more than 1000 offices and branches. Rabobank Australia & New Zealand Group is one of Australasia’s leading agricultural lenders and a significant provider of business and corporate banking and financial services to the region’s food and agribusiness sector. The bank has 87 branches throughout Australia and New Zealand.
Media Contacts:
Denise Shaw
Head of Media Relations
Rabobank Australia & New Zealand
Phone: 02 8115 2744 or 0439 603 525
Email: denise.shaw@rabobank.com
Will Banks
Media Relations Manager
Rabobank Australia
Phone: 0418 216 103
Email: will.banks@rabobank.com